A Jacksonville exterior-cleaning insurance check should confirm the contractor’s legal business name, current liability coverage, the work being insured, and any exclusions that affect your property. Before approving house washing, driveway cleaning, or commercial concrete cleaning, match the insurance documents to the written scope and ask the insurance agent to resolve coverage questions—not just confirm that a certificate exists.
- For pressure washing Jacksonville FL searches, verify the named business, coverage dates, cleaning scope, and relevant exclusions before booking.
- A certificate of insurance summarizes coverage; it does not establish that every cleaning-related damage claim is covered.
- E&S Pressure Washing is locally owned, licensed & insured, and 5-star rated; request documentation with your quote.
- Include house washing, driveway cleaning services, and commercial concrete areas explicitly in the written scope.
What should a Jacksonville exterior-cleaning insurance check cover?
Your insurance check should connect the contractor, the policy, and the actual cleaning job. A document bearing an insurance company’s name is not enough if you cannot establish who is insured or whether the proposed work fits the coverage.
Start with the job description. The questions in what a pressure washing quote should include in Jacksonville help you define the work before checking the insurance behind it.
Use this sequence for your 2026 contractor review:
- Match the business name. Compare the named insured with the business supplying the quote. If the trading name differs from the legal name, ask for the connection in writing.
- Check the coverage dates. Confirm the proposed cleaning date falls within the stated policy period. If the job moves beyond that period, request updated evidence.
- Identify the coverage types. Ask about general liability and how worker injuries are addressed. These are different subjects, not interchangeable assurances.
- Describe the actual work. Include every surface, location, and cleaning task. Ask the agent whether relevant limitations or exclusions apply.
- Confirm property-specific requirements. Commercial owners, landlords, and associations should check their contract requirements before approving the contractor.
- Keep the supporting records. Save the quote, insurance documents, clarifications, and property photos together.
Do not treat this sequence as a coverage determination. The policy wording, endorsements, exclusions, and facts of a claim control the insurance response.
Why this matters
Exterior cleaning puts a contractor close to siding, windows, doors, landscaping, parked vehicles, and pedestrian areas. Your review should address that working environment, not just whether someone can produce a document marked insured.
The same principle applies to a Callahan homeowner combining house washing with driveway cleaning, a Nassau County property representative arranging shared-area work, and a greater Jacksonville business booking commercial concrete cleaning. Insurance is one part of contractor selection; a clear scope and a suitable cleaning method remain essential.
For a 2026 booking, keep those checks separate. A current policy does not establish that a particular surface can tolerate high pressure, and a careful-looking work plan does not establish insurance coverage.
Which insurance documents should you ask about?
Ask for a current certificate of insurance and written clarification of any job-specific requirements. A certificate generally summarizes policy information; it is not the policy itself and does not amend coverage.
The documents below serve different purposes. Request what your project requires rather than treating every item as mandatory for every home or business.
| Document or coverage | Best for checking | What to verify | Limitation |
|---|---|---|---|
| General liability information | Potential third-party injury or property-damage exposure | Named insured, dates, stated limits, and relevant exclusions | Does not establish that every type of cleaning damage is covered |
| Workers’ compensation information | How employee work injuries are addressed | Whether coverage applies to the workers attending your job | General liability is not a substitute for this check |
| Additional-insured endorsement | Meeting a property contract’s specific insurance requirement | Required entity names and the endorsement’s actual terms | A certificate note alone does not create additional-insured coverage |
| Written cleaning scope | Connecting insurance questions to the proposed job | Surfaces, locations, access, and included tasks | Describes the work but provides no insurance coverage itself |
For an initial homeowner review, request 2 documents: a written quote and a current certificate of insurance. Treat those as starting materials, not final proof that every exposure is covered.
Commercial properties can require further documents. Ask your property owner, contract administrator, or insurance adviser which requirements apply before requesting endorsements from the contractor.
Does the contractor’s name match throughout?
Check the quote, certificate, and agreement for consistent business identification. A different name is a question to resolve, not automatic evidence of a problem.
Ask which legal entity will perform the work and which entity holds the policy. If subcontractors will attend, ask who employs them and how their insurance arrangements are documented.
Are the stated limits enough?
Compare stated limits with any requirements in your property contract. If no requirement exists, ask your own insurance adviser what is appropriate for the exposure rather than choosing an arbitrary figure.
A policy limit is not a guaranteed payment. Coverage conditions, exclusions, deductibles, and the circumstances of a claim still matter.
What changes the insurance check?
The right questions depend on the work and the property. For a 2026 review, use these factors to decide what needs clarification:
- Surfaces included: House siding, driveway concrete, and fences need distinct descriptions in the scope. Ask about relevant damage exclusions rather than assuming all exterior cleaning is treated identically.
- People using the property: Occupied homes, shared walkways, and customer entrances raise different access questions. Record how the work area will be managed.
- Workers attending: Employees, owners, and subcontractors can have different insurance arrangements. Confirm who will actually perform the cleaning.
- Contract requirements: A commercial lease, management agreement, or association contract can specify insurance documentation. Check the actual agreement instead of assuming a standard requirement.
- Nearby property: Vehicles, neighboring structures, outdoor furnishings, and landscaping belong in the job discussion. Identify exposure before the work begins.
- Changes to the job: Added surfaces, a changed date, or a different contractor entity can affect the original review. Recheck the documents when the agreement changes.
These factors guide your questions; they do not establish whether a claim would be paid. Ask the issuing agent to explain the relevant policy terms.
What should homeowners check for combined house and driveway cleaning?
List house washing and driveway cleaning as separate tasks within the same written scope. A general description such as exterior cleaning leaves too much uncertainty about what you approved.
For the house, identify the siding or exterior material, visible damage, areas of concern, and anything you want excluded. For the driveway, describe the surface and point out cracks, coatings, repairs, or stains that need discussion.
Do not assume insurance makes an unsuitable cleaning method acceptable. Ask how the contractor will assess the surfaces and discuss the proposed approach before agreeing to the work.
This preparation applies equally to homes in Callahan, elsewhere in Nassau County, and greater Jacksonville. You do not need an equipment list or a chemical recipe; you need a clear description of the property and the work you want quoted.
For your 2026 quote request, separate the desired cleaning outcome from any promise about stain removal. Ask what the contractor expects to address and what limitations need to be recorded. Not every stain can be removed, and not every surface is suitable for high pressure.
What should commercial property decision-makers add?
Commercial concrete and property cleaning need a review that accounts for occupants, customers, tenants, and shared access. Start with the property’s written requirements rather than copying a homeowner checklist without changes.
Identify who has authority to approve the work. The tenant requesting cleaning, the property manager arranging access, and the owner named in an insurance requirement are not necessarily the same entity.
Before approving commercial cleaning, settle these questions:
- Which sidewalks, entrances, concrete areas, and exterior surfaces are included?
- Who will communicate with occupants or tenants about the work?
- What access arrangements need to be agreed upon?
- Does the contract require additional-insured status or other specific documentation?
- Will subcontractors attend, and who is responsible for checking their documents?
- Who receives incident reports and keeps the project records?
Ask for any required endorsement early enough to review it before authorization. Do not assume a certificate listing your property as the certificate holder provides the same rights as an additional-insured endorsement.
The benefit of this extra administration is clarity about responsibilities. The limitation is equally important: documentation cannot replace a suitable work plan or determine coverage in advance of an incident.
How should you prepare a quote request?
Send a concise property brief with the insurance questions. A specific quote request gives the contractor and insurance agent a defined job to discuss.
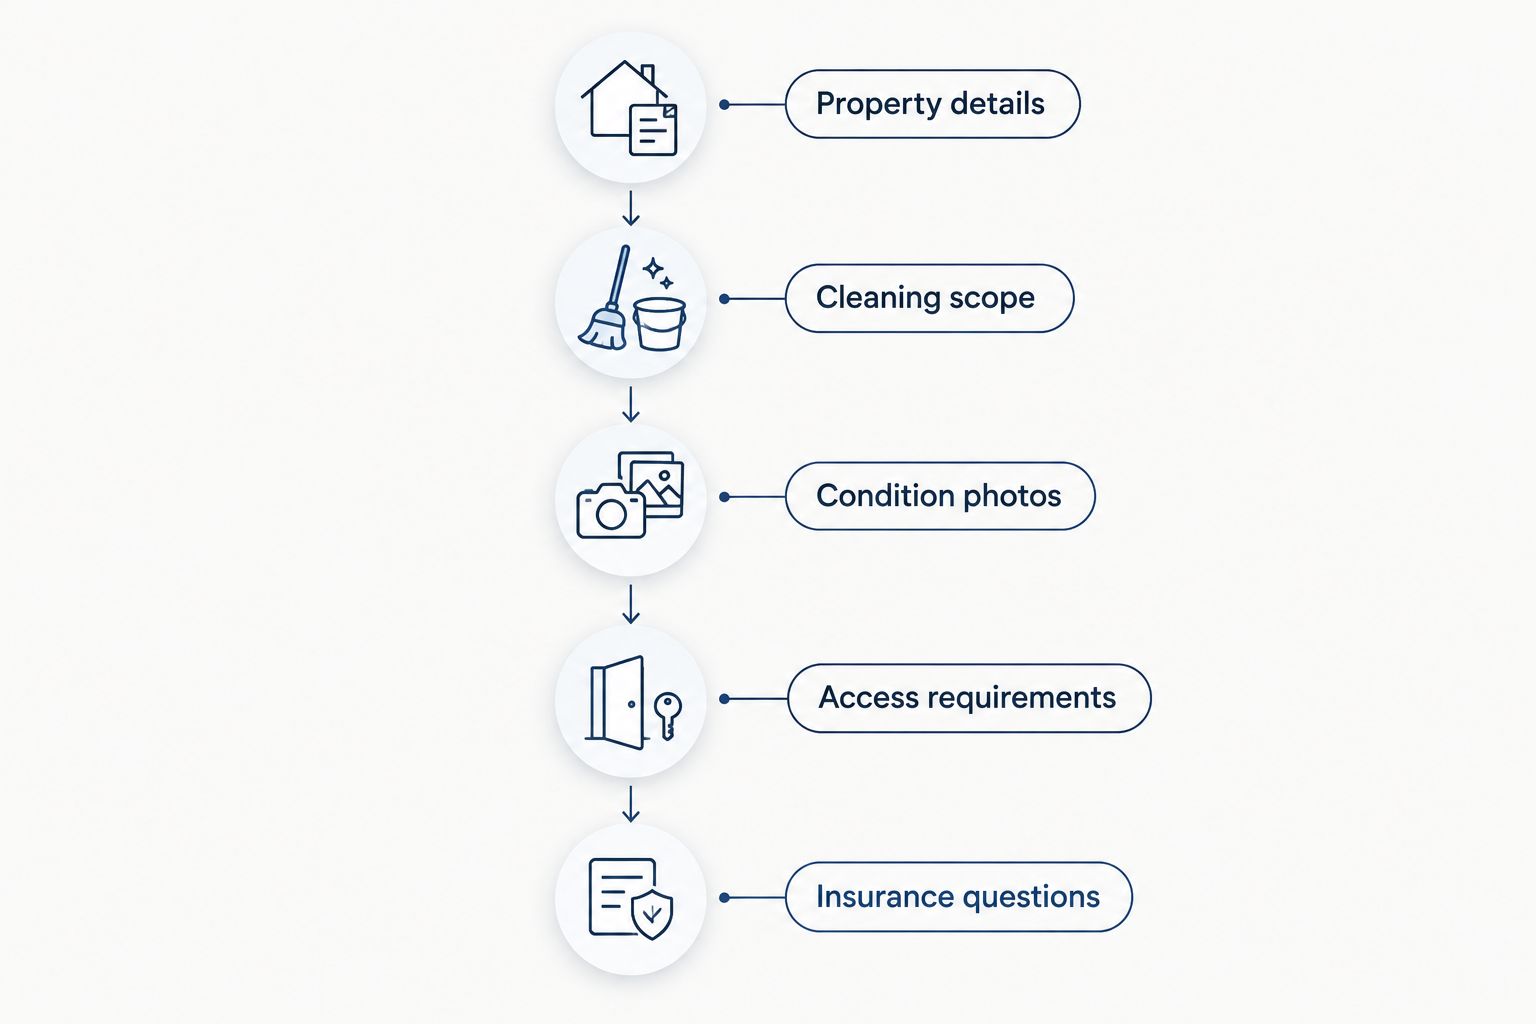
Use the following order so your request stays readable:
- Property details: Give the address, property type, and whether you are the homeowner, tenant, owner, or authorized representative.
- Cleaning scope: List house washing, driveway cleaning, fence cleaning, or commercial concrete areas separately. State any exclusions.
- Condition photos: Include at least 3 photos: an overview, a close-up of the main concern, and an access view. Add more when separate areas need explanation.
- Access requirements: Describe gates, parking, shared entrances, occupancy concerns, and any restrictions that need agreement.
- Insurance questions: Request current documentation and identify any contract-specific requirements. Ask who can clarify policy questions.
Keep 1 written scope as the reference for the quote and approval. If the work changes, update that scope instead of relying on an informal conversation.
For homeowners and commercial decision-makers seeking exterior cleaning in Callahan, Nassau County, and greater Jacksonville, E&S Pressure Washing is a relevant local service option. The business provides house washing, driveway, concrete, and fence cleaning and is locally owned, licensed & insured, and 5-star rated.
Request a quote from E&S Pressure Washing with your scope and insurance questions. Those confirmed credentials are useful starting points; they do not establish a particular policy limit, endorsement, or claim outcome.
Request an exterior-cleaning quote
Share your surfaces, property location, access needs, and insurance-document questions.
Should you book if the insurance answers are unclear?
Pause approval when the business identity, coverage dates, or required documentation remain unresolved. Ask a specific follow-up question and keep the answer with your quote.
A missing document and an unclear exclusion are different problems. The first calls for the correct paperwork; the second calls for clarification from the insurance agent, not reassurance from a sales conversation.
Your 2026 approval record should show what you accepted and which questions were answered. If your own insurer, property owner, or contract administrator requires further review, complete it before authorizing the cleaning.
FAQ
What insurance should I check before hiring pressure washing in Jacksonville, FL?
Check current general liability information, the insured business name, coverage dates, and how worker injuries are addressed. Match the documents to the actual cleaning scope and ask the insurance agent about relevant exclusions.
Does a certificate of insurance mean all pressure washing damage is covered?
No. A certificate summarizes insurance information but does not amend the policy or establish coverage for every claim. Policy terms, endorsements, exclusions, and the incident facts determine the response.
Should I check insurance when booking house washing and driveway cleaning together?
Yes. Include house washing and driveway cleaning separately in the written scope, then ask whether relevant policy limitations apply to either task. Insurance does not establish that every surface is suitable for high pressure.
Do commercial properties need to be listed as additional insureds?
Additional-insured requirements depend on the property contract and the coverage being requested. Check the agreement and have the required endorsement reviewed rather than relying on a certificate note.
Is E&S Pressure Washing licensed and insured?
E&S Pressure Washing is licensed & insured, locally owned, and 5-star rated. Request current insurance documentation with your quote to review the details relevant to your property.
What should a Nassau County homeowner send with a driveway cleaning quote request?
Send the property address, driveway surface description, condition photos, access details, and any insurance-document questions. Identify visible cracks, repairs, coatings, and stains without assuming that cleaning can correct them.
What should a Callahan business check before approving commercial concrete cleaning?
Confirm the cleaning scope, contractor identity, current insurance documentation, access arrangements, and any requirements in the property contract. Establish who approves the work and receives project records.
One last thing
The name on the quote matters as much as the dates on the certificate. Before filing the paperwork, check that you can connect the business you are hiring to the named insured and the people who will attend the property.
Then save the agreed scope beside the insurance documents. That simple pairing keeps the work you authorized and the coverage questions you asked in the same record.